Engineers India Limited: Consultancy-Led Margins, a Record Order Book and a Widening Diversification Bet
NSE: ENGINERSIN | BSE: 532178
A) About Engineers India Limited
Engineers India Limited (EIL) is a Navratna Government of India enterprise under the Ministry of Petroleum and Natural Gas, operating as a global engineering consultancy, project management and total solutions company. Incorporated in 1965 and listed on the BSE and NSE, EIL has delivered over 8,000 assignments, including more than 700 major projects, and has built a leadership position across India’s oil and gas value chain, with footprints in 20 of the country’s 23 refineries and 12 of its 13 mega petrochemical complexes.
The company operates through two segments, Consultancy and Engineering, and Turnkey (LSTK/EPC/OBE), and has been steadily diversifying beyond hydrocarbons into infrastructure, fertilizers, water and waste water management, coal gasification, green hydrogen, nuclear balance-of-plant work and data centres. EIL also holds strategic minority stakes in projects such as the Ramagundam Fertilizer plant and Numaligarh Refinery, which contribute dividend income. The company carries virtually no debt (borrowings of about Rs 17 crore against a net worth of over Rs 3,100 crore) and sits on a large cash and investment book built up over decades of consultancy cash flows.
| Particulars | Details |
|---|---|
| Industry | Engineering Consultancy / Oil & Gas EPC |
| Chairman & Managing Director | Shri Atul Gupta |
| Director (Finance) | Shri Sanjay Jindal |
| Registered Office | Engineers India Bhawan, 1, Bhikaji Cama Place, New Delhi – 110066 |
| Listed Since | 1997 (BSE and NSE) |
| Face Value | Rs 5 per share |
| Promoter Holding | 51.32% (Government of India) |
B) Key Market Indicators
| Particulars | Value |
|---|---|
| CMP / Market Cap | Rs 306 / approx Rs 17,200 crore |
| 52-Week Range | Rs 164 – Rs 309 |
| TTM PE | 21.9x |
| Price to Book | 5.5x |
| ROCE / ROE | 30.4% / 23.4% |
| TTM EPS | Rs 13.95 |
C) Business Segments
Consultancy and Engineering is EIL’s core, higher-margin business, spanning feasibility studies, FEED, detailed engineering, project management consultancy (PMC) and EPCM services for refining, petrochemicals, pipelines, fertilizers and, increasingly, non-hydrocarbon sectors such as infrastructure, nuclear balance-of-plant and coal gasification. This segment has consistently earned segment margins in the 20-30% range and management has explicitly stated its strategy is to keep consultancy revenue at 50-60% of the mix given its superior profitability.
Turnkey (LSTK/EPC/OBE) covers larger execution-heavy contracts, mostly on an open book estimate (OBE) basis, where EIL takes on procurement and construction responsibility alongside engineering. This segment carries thinner margins (7-8% typically) and can be lumpy depending on project stage, but it is where the company’s largest overseas wins, such as the Dangote refinery and fertilizer project in Nigeria, sit.
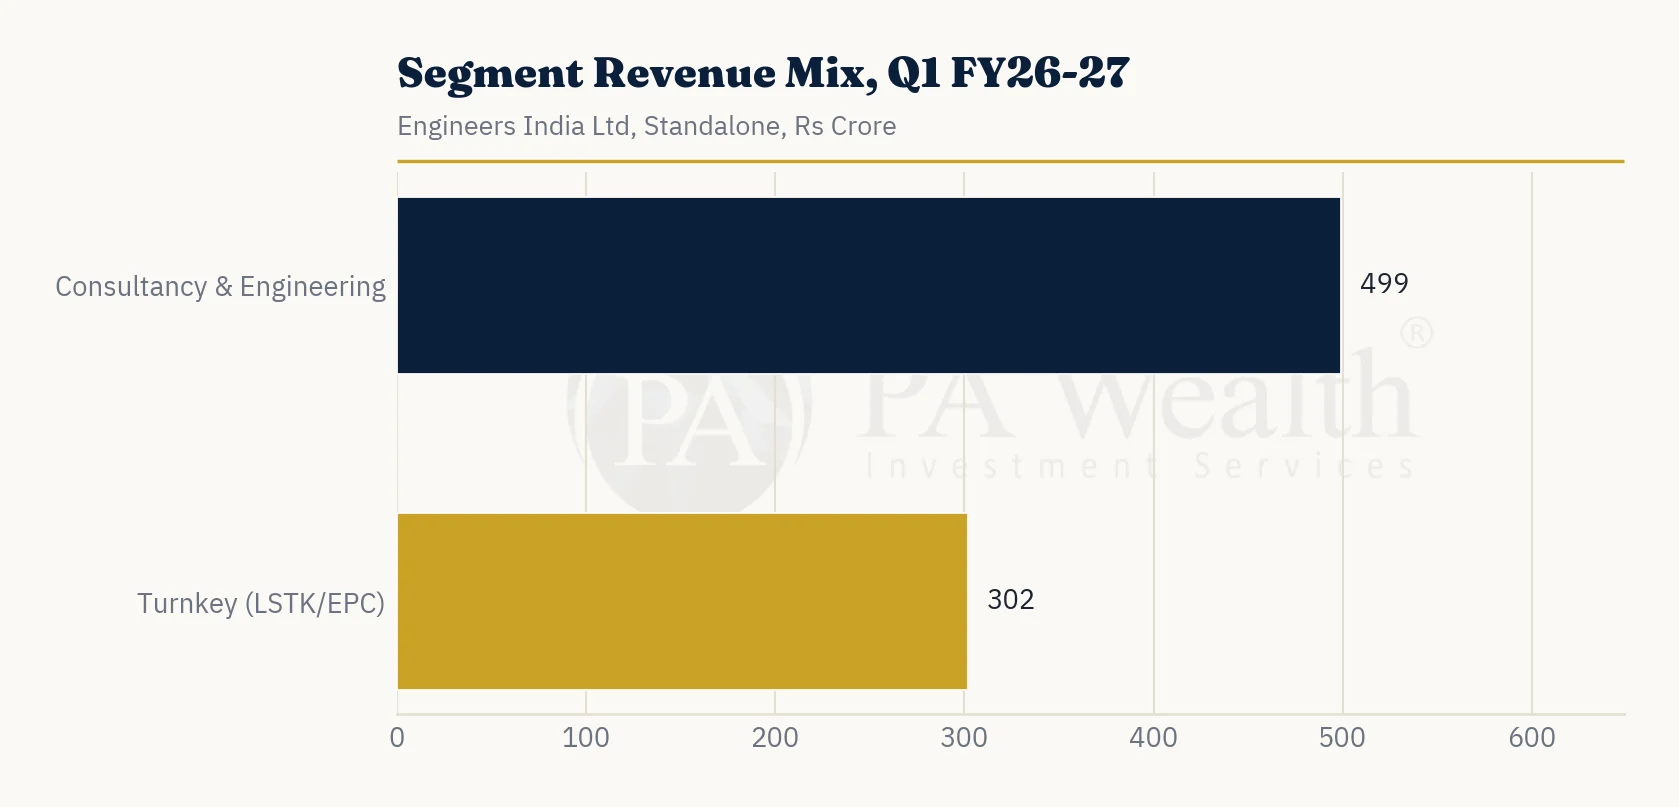
In the June 2026 quarter, Consultancy contributed about 62% of standalone turnover and Turnkey about 38%, continuing the multi-year shift toward consultancy that management expects to sustain in FY27.
D) Shareholding Pattern
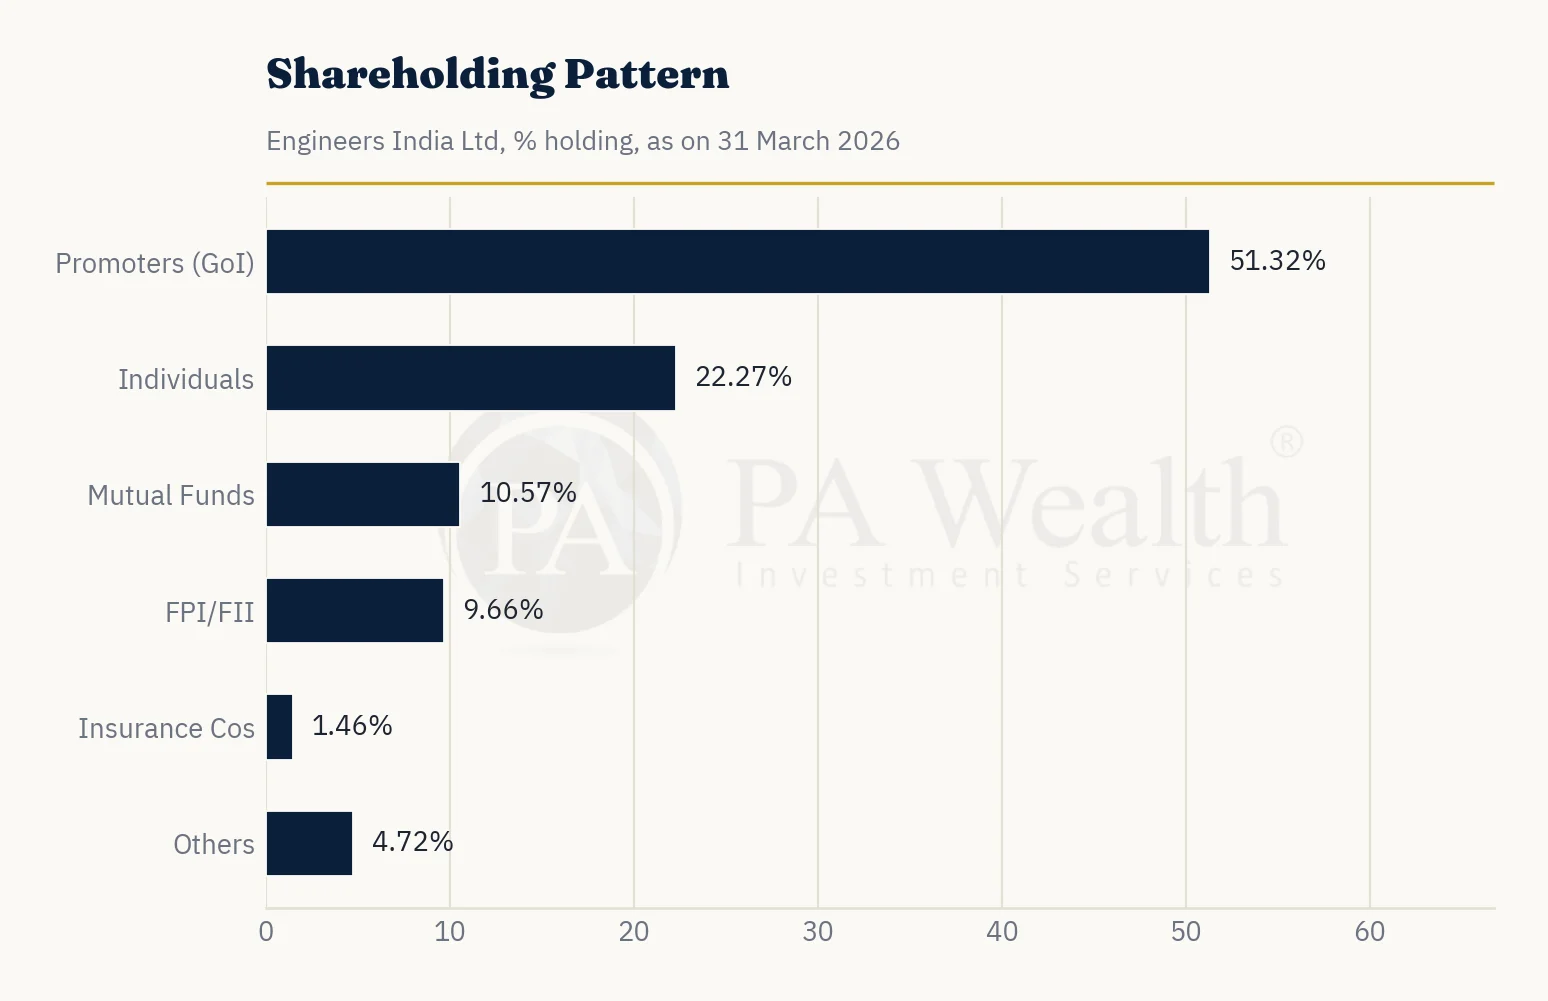
The Government of India remains the majority owner at 51.32%, with the balance held by individuals, domestic mutual funds, foreign portfolio investors and insurance companies. Institutional ownership (mutual funds plus FPI) stood at just over 20% as on 31 March 2026.
| Category | % Holding (31 Mar 2026) |
|---|---|
| Promoters (Government of India) | 51.32% |
| Individuals | 22.27% |
| Mutual Funds | 10.57% |
| Foreign Portfolio Investors | 9.66% |
| Insurance Companies | 1.46% |
| Others | 4.72% |
E) Financials
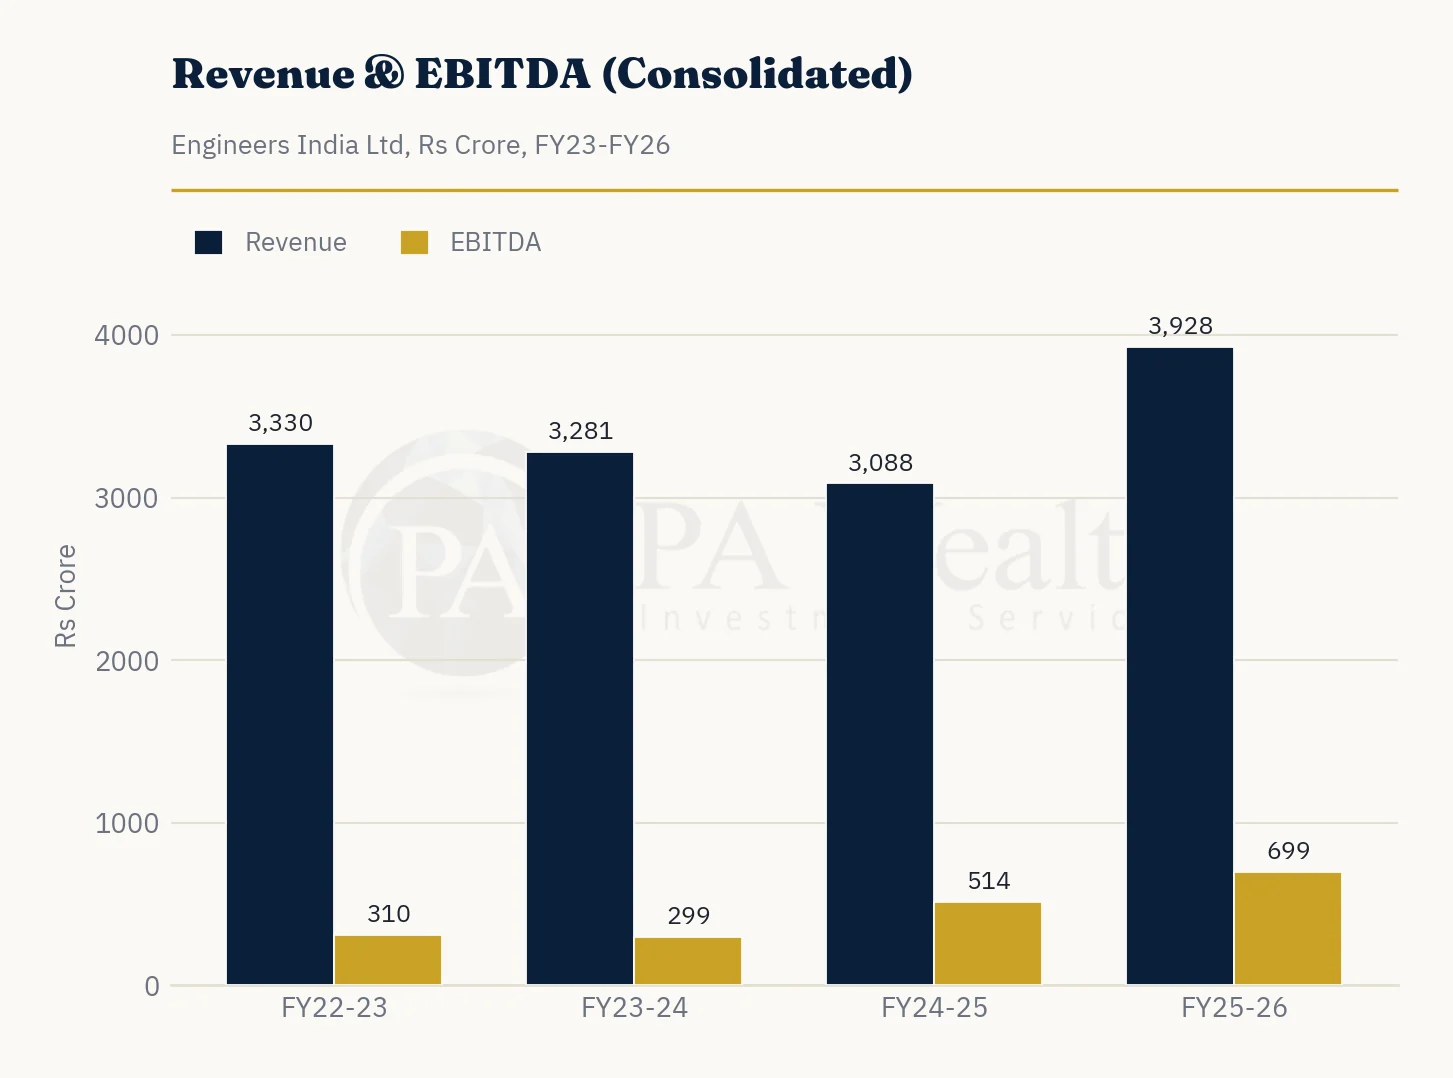
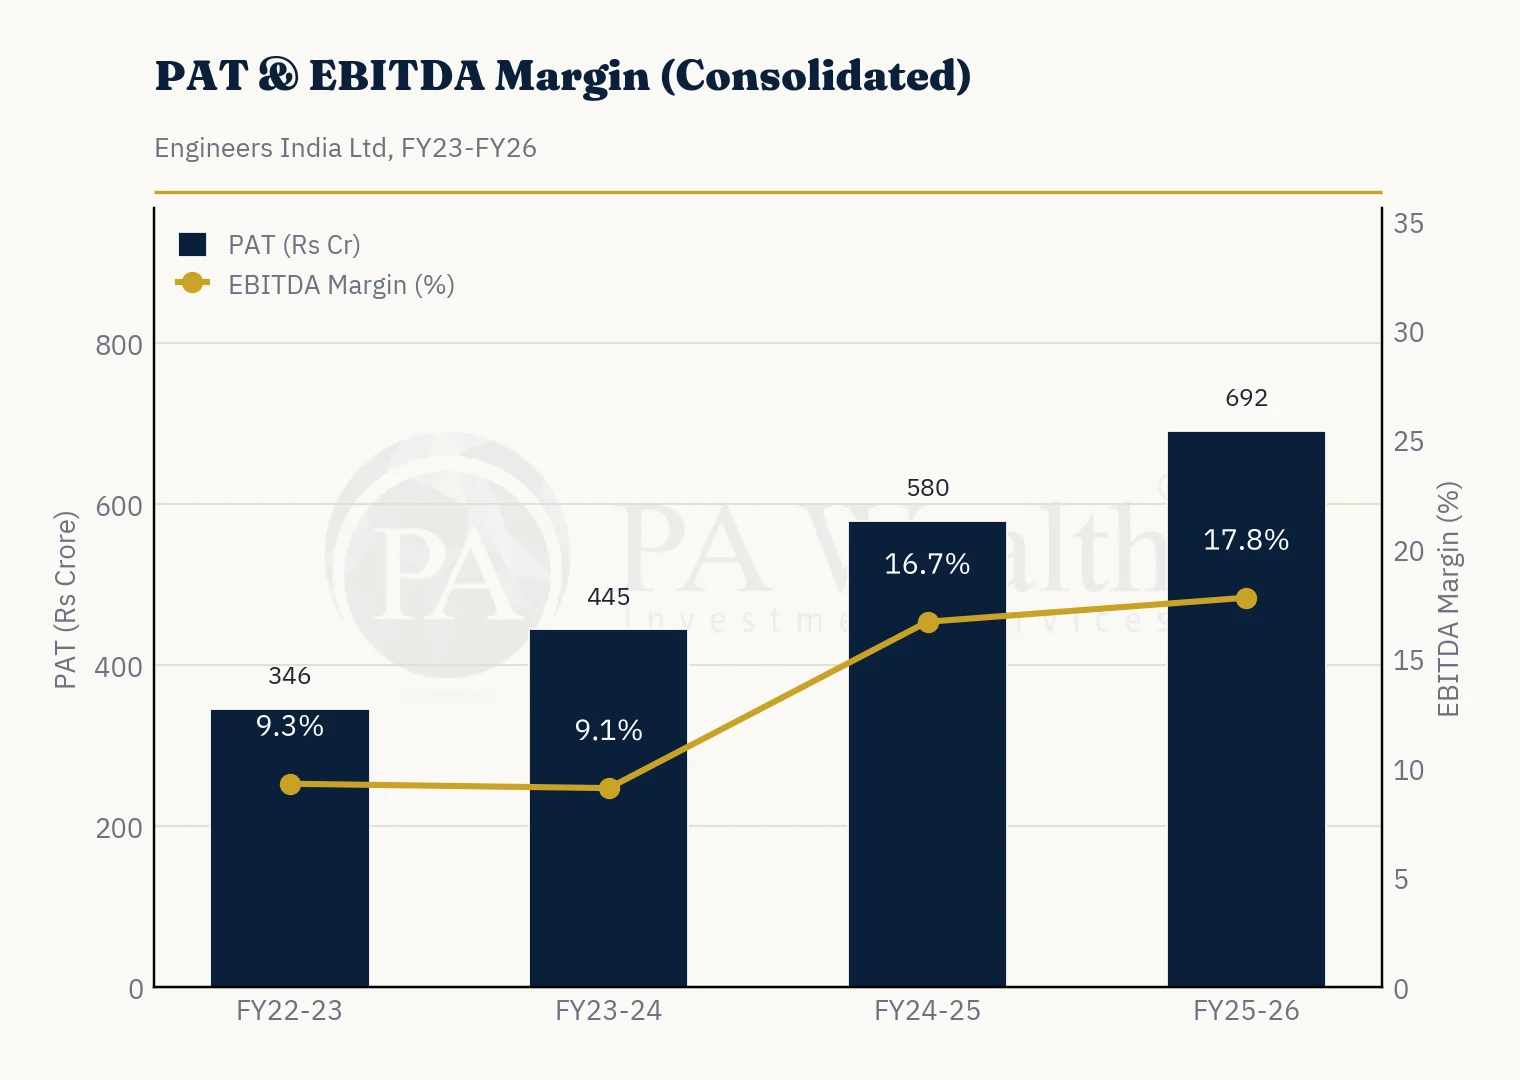
On a consolidated basis, EIL’s revenue was largely range-bound between FY23 and FY25 before stepping up sharply in FY26 on the back of stronger Turnkey execution and a richer consultancy mix. EBITDA margins have nearly doubled over the same period as the revenue mix has tilted toward higher-margin consultancy work and legacy low-margin Turnkey contracts have rolled off.
| Particulars (Rs Cr) | FY22-23 | FY23-24 | FY24-25 | FY25-26 | 3-Yr CAGR |
|---|---|---|---|---|---|
| Revenue | 3,330 | 3,281 | 3,088 | 3,928 | 5.7% |
| EBITDA | 310 | 299 | 514 | 699 | 31.2% |
| EBITDA Margin | 9.3% | 9.1% | 16.7% | 17.8% | – |
| PAT | 346 | 445 | 580 | 692 | 26.2% |
| EPS (Rs) | 6.16 | 7.92 | 10.31 | 12.31 | 26.1% |
F) Management Discussion and Highlights (Q1 FY26-27)
- Standalone profit after tax rose 55% YoY to Rs 109 crore, with profit before tax up 55% YoY to Rs 145 crore.
- Consolidated PAT more than doubled to Rs 157.94 crore versus Rs 65.4 crore a year ago, aided by a swing to profit at the company’s joint ventures (Rs 42.51 crore profit versus a Rs 7.37 crore loss last year) and higher CEIL subsidiary profit (up 155% YoY).
- Standalone EBITDA margin expanded sharply to 18.55% from 11.72% in Q1 FY26, driven by a 22% YoY jump in Consultancy revenue to Rs 499 crore, even as Turnkey revenue declined to Rs 302 crore from Rs 449 crore on the back of tapering execution on older projects.
- Order book stood at Rs 14,424 crore as on 30 June 2026 (Consultancy Rs 10,498 crore, Turnkey Rs 3,926 crore), with year-to-date order inflow of about Rs 2,750 crore against a full-year FY27 target of Rs 8,000 crore that management reiterated confidence in meeting or exceeding.
- Despite a cautious Middle East environment following regional geopolitical tensions, EIL secured over Rs 500 crore of new business from the region in Q1 alone and said existing overseas projects continue uninterrupted.
- Management flagged growing opportunities in nuclear (balance-of-plant consultancy, environmental impact studies for private and government clients), coal gasification (following a government gap-funding push of Rs 34,000 crore) and infrastructure, including a new data centre assignment.
- The company reiterated its FY28 revenue target of Rs 5,000 crore and guided to a full-year FY27 operating margin of around 16%, with room for improvement if pending change orders with clients are finalized.
G) Strengths & Weaknesses
Strengths:
- Navratna PSU status with a 60-year track record and near-monopoly credentials across India’s refining and petrochemical value chain.
- Debt-free balance sheet with over Rs 1,360 crore of cash and Rs 1,600 crore of investments, funding both dividends and new strategic stakes.
- Consultancy-led revenue mix (60%-plus of turnover) that carries structurally higher margins than Turnkey execution.
- Record order book of Rs 14,424 crore, roughly 3.7 times FY26 standalone turnover, offering multi-year revenue visibility.
- Consistent dividend track record, with payout near 100% of profit in FY26.
- Credible diversification pipeline across nuclear, green hydrogen, coal gasification, data centres and infrastructure, reducing dependence on the hydrocarbon capex cycle.
Cautions & Key Risks:
- Order inflows are lumpy and concentrated in a small number of large overseas and domestic contracts, which can cause sharp swings between quarters.
- Middle East geopolitical uncertainty has slowed new mega-project tenders from key clients such as Saudi Aramco, even as existing work continues.
- Turnkey/LSTK revenue and margins remain volatile and are tied to the execution stage of a handful of large projects.
- Large prospective orders (BPCL Andhra Pradesh refinery, IOCL Paradip Phase 2, ONGC petrochemicals) remain at feasibility or client-approval stages with no committed timelines.
- New growth areas such as nuclear and coal gasification are still at an early, low-revenue stage and their eventual contribution to order inflow is not yet proven at scale.
- As a Government of India enterprise, capital allocation decisions, including any move toward higher shareholder returns from the growing cash pile, remain subject to government guidance.
H) Outlook
Engineers India enters FY27 with its highest-ever order book, a consultancy mix that is structurally improving profitability, and a widening set of non-hydrocarbon opportunities that reduce its historical dependence on refinery and petrochemical capex cycles. The near-term setup looks constructive: management has reiterated its Rs 8,000 crore order inflow target and a medium-term Rs 5,000 crore revenue ambition for FY28, while margins have already re-rated meaningfully from the single-digit EBITDA levels of FY23-24. The key swing factors to watch are the pace at which large domestic prospects such as the BPCL Andhra Pradesh refinery and IOCL Paradip Phase 2 convert into firm orders, how quickly emerging segments like nuclear and coal gasification scale from studies to executable contracts, and whether Middle East order flow normalizes as regional tensions ease. For investors comfortable with the cyclicality inherent in project-based consultancy and execution businesses, EIL offers a rare combination of a debt-free, cash-generative PSU balance sheet with genuine optionality on India’s energy transition and infrastructure build-out.
Drop us your query at – info@pawealth.in or Visit pawealth.in
References: Engineers India Limited Integrated Annual Report FY2025-26, Investor Presentation (Annual Results FY25-26), Q1 FY26-27 Earnings Call Transcript (14 August 2026), Screener.in financial data.
Disclaimer: This report is for informational purposes only and does not constitute investment advice or a recommendation to buy or sell any security. Past performance is not indicative of future results. Investors should consult their financial advisor and conduct their own due diligence before making any investment decisions. PA Wealth Private Limited and its representatives may hold positions in the securities discussed.