Computer Age Management Services (CAMS) is the back office of India’s mutual fund industry. Every time an investor starts a SIP, redeems units or updates a KYC with most large fund houses, the transaction runs through CAMS. With about 68% market share, it is a direct play on the growth of Indian mutual funds, and it is now building a second engine in non-MF businesses such as payments, alternatives and KYC.
(A) About CAMS
Founded in 1988 and headquartered in Chennai, CAMS is India’s largest Registrar and Transfer Agent (RTA) for mutual funds. It services 10 of the 15 largest fund houses, with an average relationship of over 23 years with its top 10 clients. The company listed on BSE in October 2020 and later on NSE. It has no promoter: Warburg Pincus (Great Terrain) and NSE exited earlier, making CAMS fully publicly owned. It is debt-free and held about Rs 980 crore of cash in June 2026. Shares were split from Rs 10 to Rs 2 face value in December 2025.
| Particulars | Details |
|---|---|
| Industry | Capital Market Services – Registrar and Transfer Agent |
| Chairman | Mr. Dinesh Kumar Mehrotra |
| MD and CEO | Mr. Anuj Kumar |
| CFO | Mr. Ram Charan Sesharaman |
| Registered Office | New No. 10, Old No. 178, M.G.R. Salai, Nungambakkam, Chennai – 600034 |
| Listed Since | October 2020 |
| Face Value | Rs 2 |
| Promoter Holding | Nil (professionally managed) |
(B) Key Market Indicators
As on 5 November 2026.
| Indicator | Value |
|---|---|
| CMP / Market Cap | Rs 716 / about Rs 17,800 crore |
| 52-Week High / Low | Rs 845 / Rs 611 |
| TTM EPS / TTM P/E | Rs 20.6 / about 35x |
| Price / Book | About 12x |
| EV / EBITDA (TTM) | About 23x |
| ROCE / ROE | 47.0% / 36.3% |
| Dividend Yield | About 1.7% |
(C) Business Segments
- MF asset-based (74% of FY26 revenue): Fees linked to the AUM CAMS services, about Rs 55 lakh crore in March 2026. This grows with market levels and SIP flows, minus a small annual yield cut of about 2.5% to 3%.
- MF non-asset based (12%): Transaction and service fees, NFO processing and MF Central. CAMS processed 107 crore transactions in FY26, up 20%.
- Non-MF businesses (14%): CAMSPay (payment aggregator and gateway), CAMS Alternatives (about 50% share of outsourced AIF servicing), CAMS KRA (now the number 2 KYC agency), CAMSRep (40% share in insurance repository), Bima Central, account aggregator, Think360 analytics and the new ConsentPro data privacy offering.
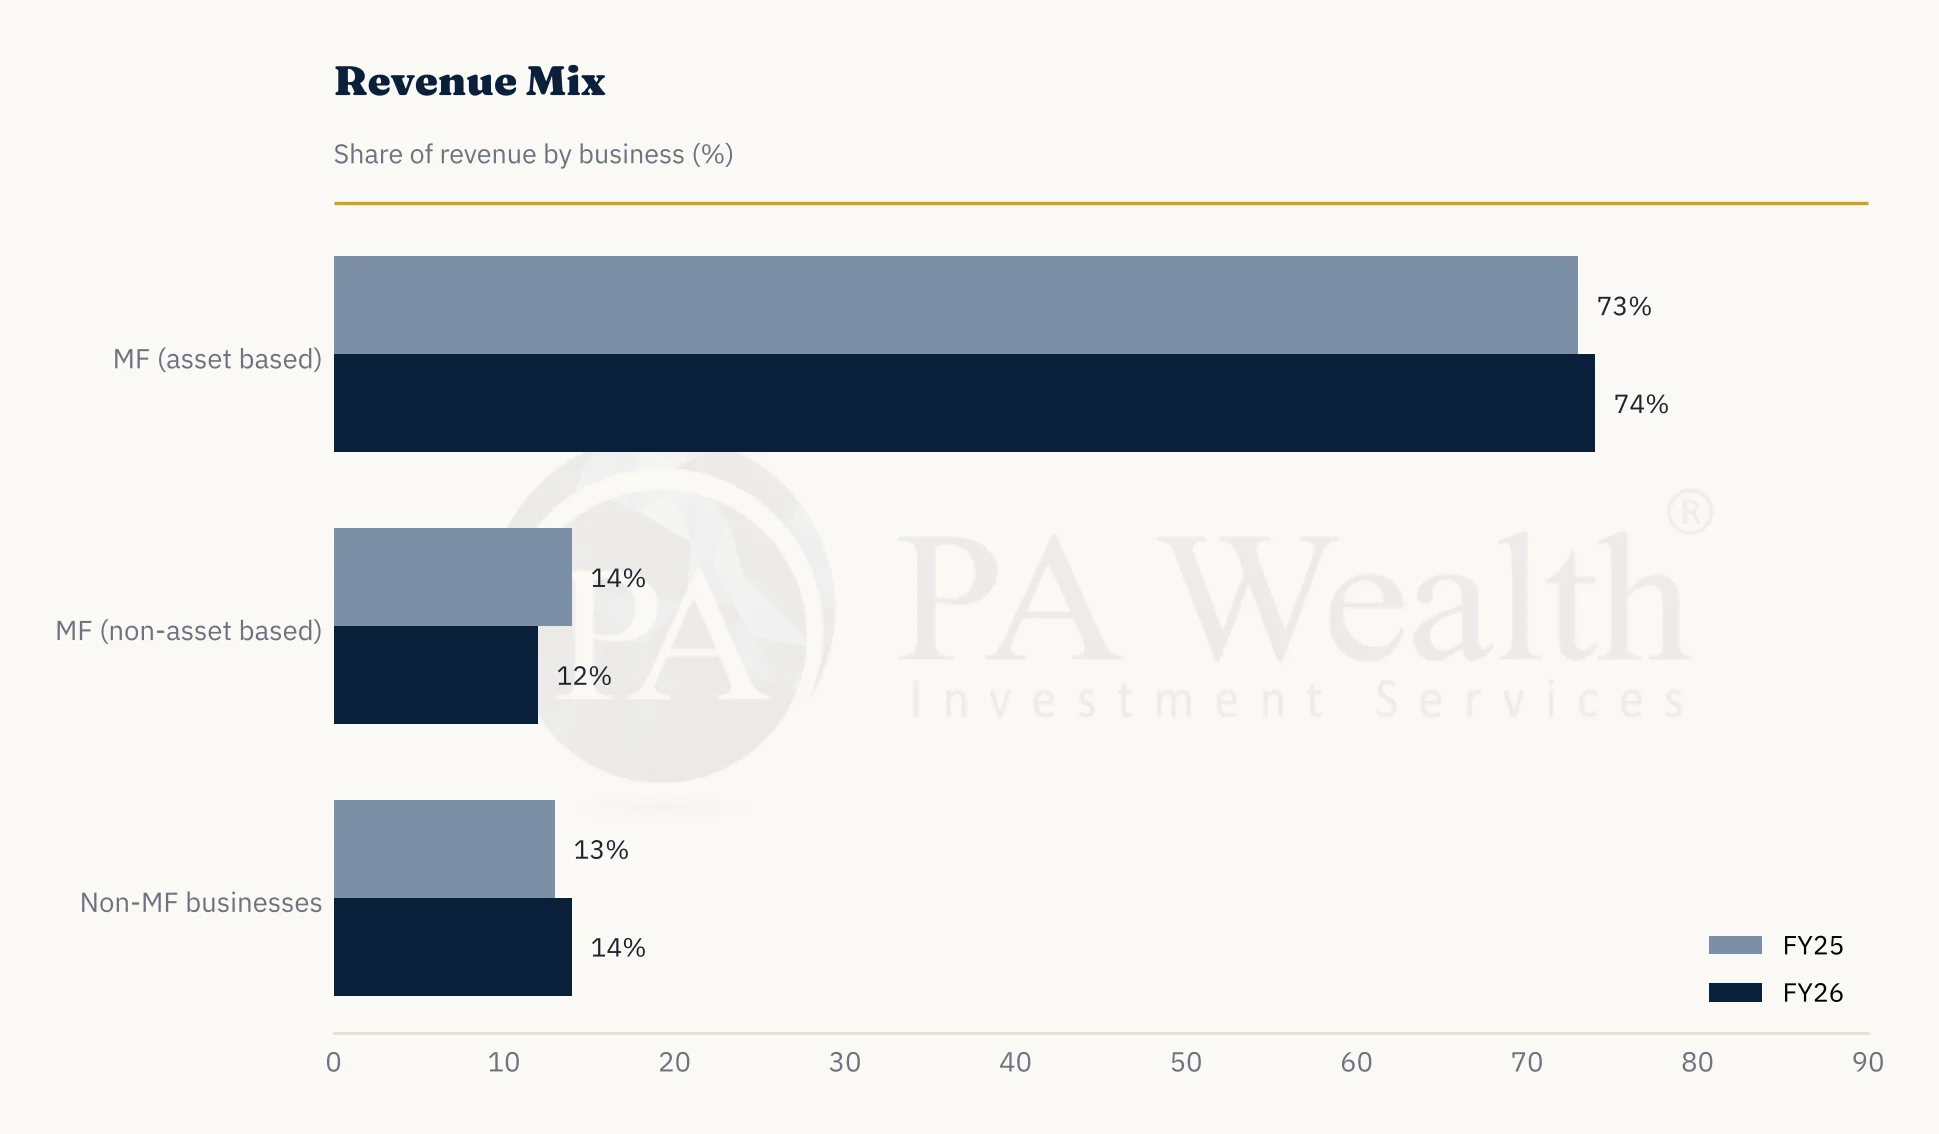
Non-MF is the growth story: it grew about 25% in Q4 FY26 and 28% in Q1 FY27, and is close to 16% of revenue now.
(D) Shareholding Pattern
| Category | Jun 2026 (%) | Sep 2026 (%) | QoQ Change |
|---|---|---|---|
| Promoters | 0.00 | 0.00 | – |
| FIIs | 44.88 | 45.58 | +0.70 |
| DIIs | 23.54 | 21.79 | -1.75 |
| Public and Others | 31.57 | 32.64 | +1.07 |
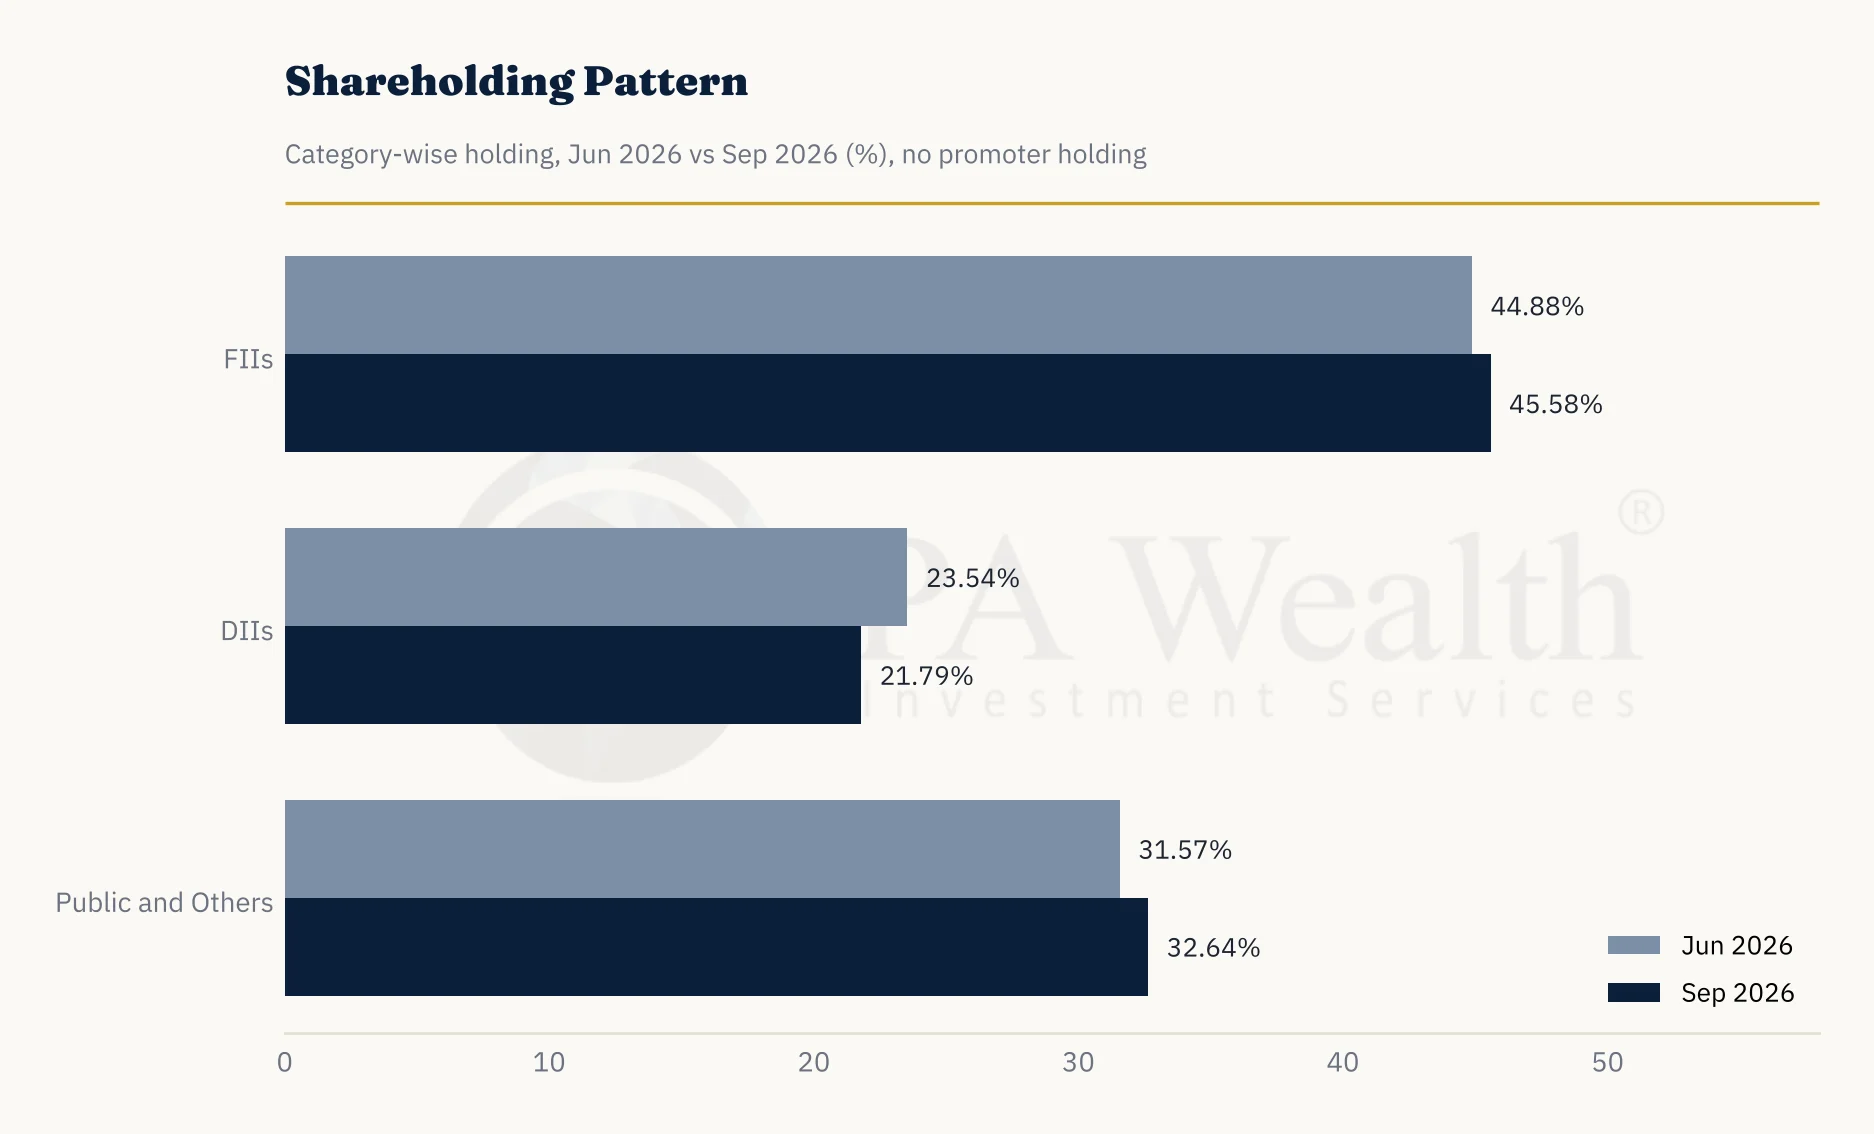
Foreign investors own the largest block and added to it in the September quarter, while domestic institutions trimmed 1.75 percentage points.
(E) Financials
Consolidated, Rs crore (EPS in Rs, split adjusted).
| Particulars | FY23 | FY24 | FY25 | FY26 | 3-Year CAGR |
|---|---|---|---|---|---|
| Revenue | 972 | 1,137 | 1,422 | 1,516 | 16.0% |
| EBITDA | 421 | 505 | 652 | 684 | 17.6% |
| EBITDA Margin (%) | 43.3% | 44.4% | 45.9% | 45.1% | – |
| PAT | 285 | 354 | 470 | 476 | 18.6% |
| EPS (Rs) | 11.65 | 14.41 | 19.08 | 19.23 | 18.2% |
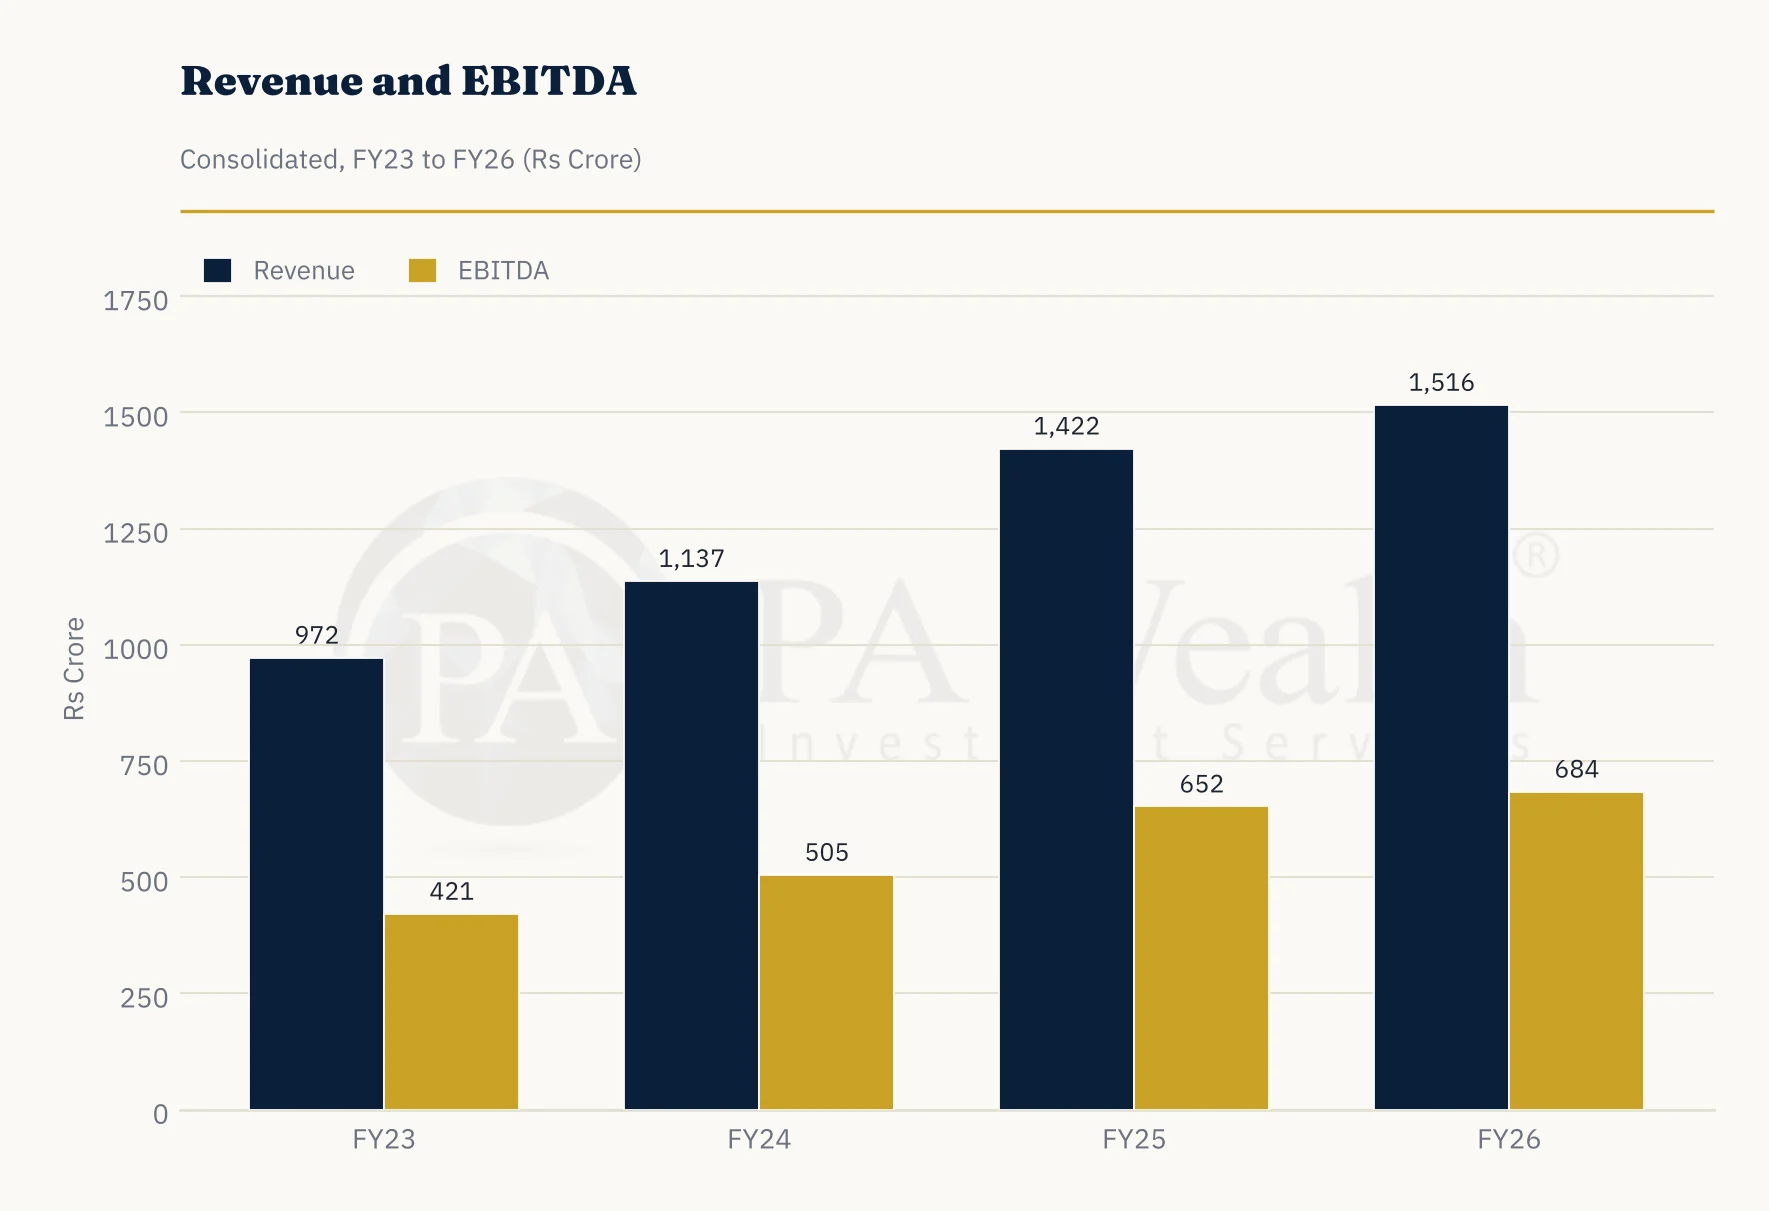
FY26 growth slowed to about 7% because of a one-time price cut given to large fund houses early in the year and weak markets in March. Return on net worth was still 39%, and CAMS paid Rs 12.50 per share in dividends for FY26, about 65% of profit.
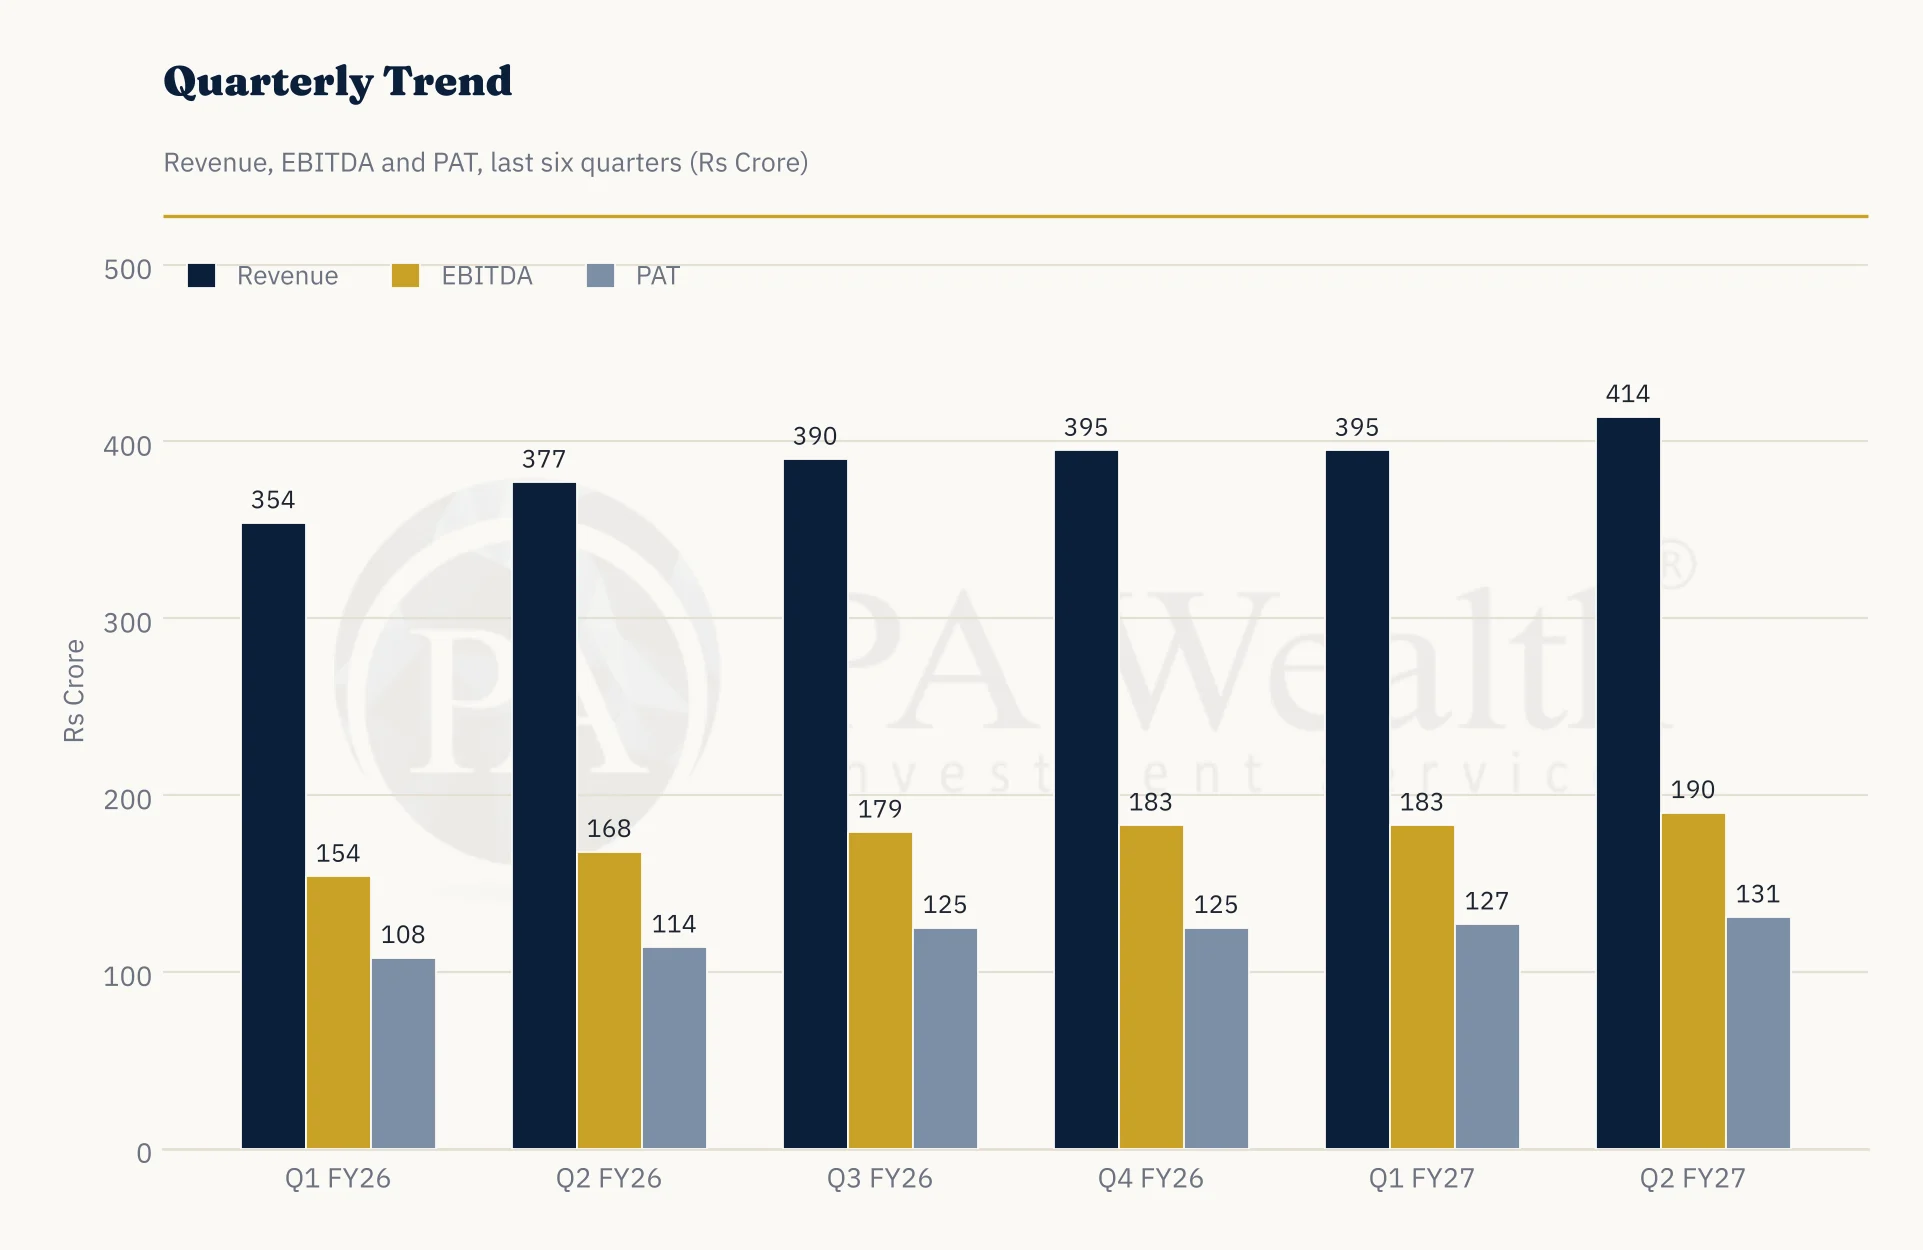
Quarterly numbers show the pricing hit is now behind the company, with EBITDA margin back above 46% for three straight quarters.
| Quarter | Revenue | EBITDA | EBITDA Margin | PAT |
|---|---|---|---|---|
| Q1 FY26 | 354 | 154 | 43.5% | 108 |
| Q2 FY26 | 377 | 168 | 44.6% | 114 |
| Q3 FY26 | 390 | 179 | 45.9% | 125 |
| Q4 FY26 | 395 | 183 | 46.3% | 125 |
| Q1 FY27 | 395 | 183 | 46.4% | 127 |
| Q2 FY27 | 414 | 190 | About 46% | 131 |
(F) Management Discussion and Highlights
- Q2 FY27 revenue grew 10% to Rs 414 crore and PAT grew 14.4% to Rs 131 crore. H1 FY27 PAT rose 15.8% to Rs 260 crore. Serviced AUM touched a record Rs 58.4 lakh crore and the client base rose to 32 AMCs.
- FY27 guidance: about 13% revenue growth and 16% EBITDA growth, with MF revenue up at least 12% and non-MF revenue up 20% or more.
- Yields are stable. The pricing reset of FY25 and FY26 is in the base, and management expects only the usual 2.5% to 3% annual yield decline.
- Equity AUM share rose to 67%, and CAMS is gaining share in equity net sales, new SIP registrations and SIP collections, the most profitable part of the industry.
- CAMSPay grew about 70% YoY in Q1 FY27 and crossed 6% of revenue. Alternatives AUM crossed Rs 3.2 lakh crore with 50 new mandates. KRA was hit by a 29% to 30% rate cut from April 2026 but is expected to recover from Q2.
- New AMC wins include AlphaGrep, Carnelian, ASK, Oaklane and Neo. New product lines such as SIFs (about Rs 12,000 crore, 11 live funds) and GIFT City retail funds are early but promising.
- A Rs 500 crore platform rebuild with AI-led automation is underway. Headcount is falling (about 8,300 now) and is expected to drop 4% to 5% in FY27, with employee cost growth held near 5% and total costs below 10%.
- Management expects EBITDA margin to expand by about 1% a year, possibly 1.5%, and non-MF margin to rise towards 17% to 20%.
(G) Strengths and Weaknesses
Strengths
- Near-duopoly with about 68% market share and decades-long client relationships.
- Direct beneficiary of rising SIPs and financialisation of household savings.
- Asset-light, debt-free model with 47% ROCE and a high dividend payout.
- Fast-growing non-MF businesses reduce dependence on mutual fund AUM.
- Automation is driving revenue growth on a falling headcount.
Cautions and Key Risks
- About 86% of revenue is linked to mutual funds, so a market fall directly hits AUM and earnings.
- The growing share of low-fee passive funds weighs on blended yields.
- Regulators can cut fees, as seen in the KRA rate revision.
- Competition from KFin Technologies for new AMC mandates.
(H) Outlook
CAMS is a high-quality toll on India’s mutual fund growth, with near-monopoly economics, high returns and a growing non-MF business. The pricing reset is now behind it, margins are back above 46%, and automation offers steady margin gains. At about 35x earnings the valuation is reasonable for its quality but depends on markets staying healthy. Long-term investors should track AUM growth, yield trends and whether non-MF revenue keeps compounding at 20% or more.
References: CAMS Annual Reports FY2024-25 and FY2025-26; Q4 FY26 and Q1 FY27 earnings call transcripts; Q2 FY27 results (29 October 2026).
Disclaimer: This blog is for educational and informational purposes only and should not be considered a recommendation to buy, sell or hold any security. Investments in securities are subject to market risks. Please read all related documents carefully and consult your financial professional before making any investment decision. PA Wealth Ventures Private Limited is a SEBI Registered Research Analyst (Reg. No. INH000020642). Past performance is not indicative of future returns.