Dr Lal PathLabs has spent two years building quietly: 32 new labs, close to 2,000 new collection centres, a revived Suburban business in Mumbai and a sharper push into preventive and specialised testing. That groundwork is now showing up in the numbers. Revenue grew 19.1% in Q1 FY27, the fastest in four years, and about 19.6% in Q2 FY27, with profit up 27% in both quarters.
(A) About Dr Lal PathLabs
Founded in 1949 by Dr Major S. K. Lal as a single pathology lab in Delhi, Dr Lal PathLabs is today one of India’s largest organised diagnostic chains, listed on NSE and BSE since 2015. As of March 2026 it ran 312 labs, 7,727 patient service centres and 13,935 pick-up points, largely franchised, and served 30.3 million patients in FY26. The promoter family holds about 53%. The company is practically debt-free, with net cash of Rs 1,693 crore (June 2026) and negative working capital of about 26 days.
| Particulars | Details |
|---|---|
| Industry | Healthcare Services – Diagnostics |
| Executive Chairman | (Hony) Brig. Dr. Arvind Lal |
| CEO | Mr. Shankha Banerjee |
| Group CFO | Mr. Ved Prakash Goel |
| Registered Office | Block E, Sector-18, Rohini, New Delhi – 110085 |
| Listed Since | 2015 |
| Face Value | Rs 10 |
| Promoter Holding | 52.93% (September 2026) |
(B) Key Market Indicators
As on 4 November 2026.
| Indicator | Value |
|---|---|
| CMP / Market Cap | Rs 2,027 / about Rs 34,000 crore |
| 52-Week High / Low | Rs 2,040 / Rs 1,272 |
| TTM EPS / TTM P/E | About Rs 35 / about 58x |
| Price / Book | About 13.5x |
| EV / EBITDA (TTM) | About 36x |
| ROCE / ROE | 28.0% / 22.3% (ROCE excluding cash: 44%) |
| Dividend Yield | About 0.7% |
(C) Business Segments
The company reports as a single diagnostics business, so it is best read by product, channel and region.
- Pathology: Routine and specialised testing forms the bulk of revenue. Around 400 routine tests are reported within 3 hours for almost 90% of walk-in patients. Specialised areas include oncology, genomics, autoimmune and reproductive health. Genomics is still under 5% of revenue.
- Swasthfit: Preventive health packages contributed 27% of FY26 revenue and are growing at around 20%.
- Channel: 75% of revenue is B2C (direct patients) and 25% B2B (hospitals and institutions).
- New bets: Sovaaka (one premium precision health centre), a few high-end radiology centres, and early international steps in Nepal, Bangladesh, Dubai and Ghana. International is under 5% of revenue.
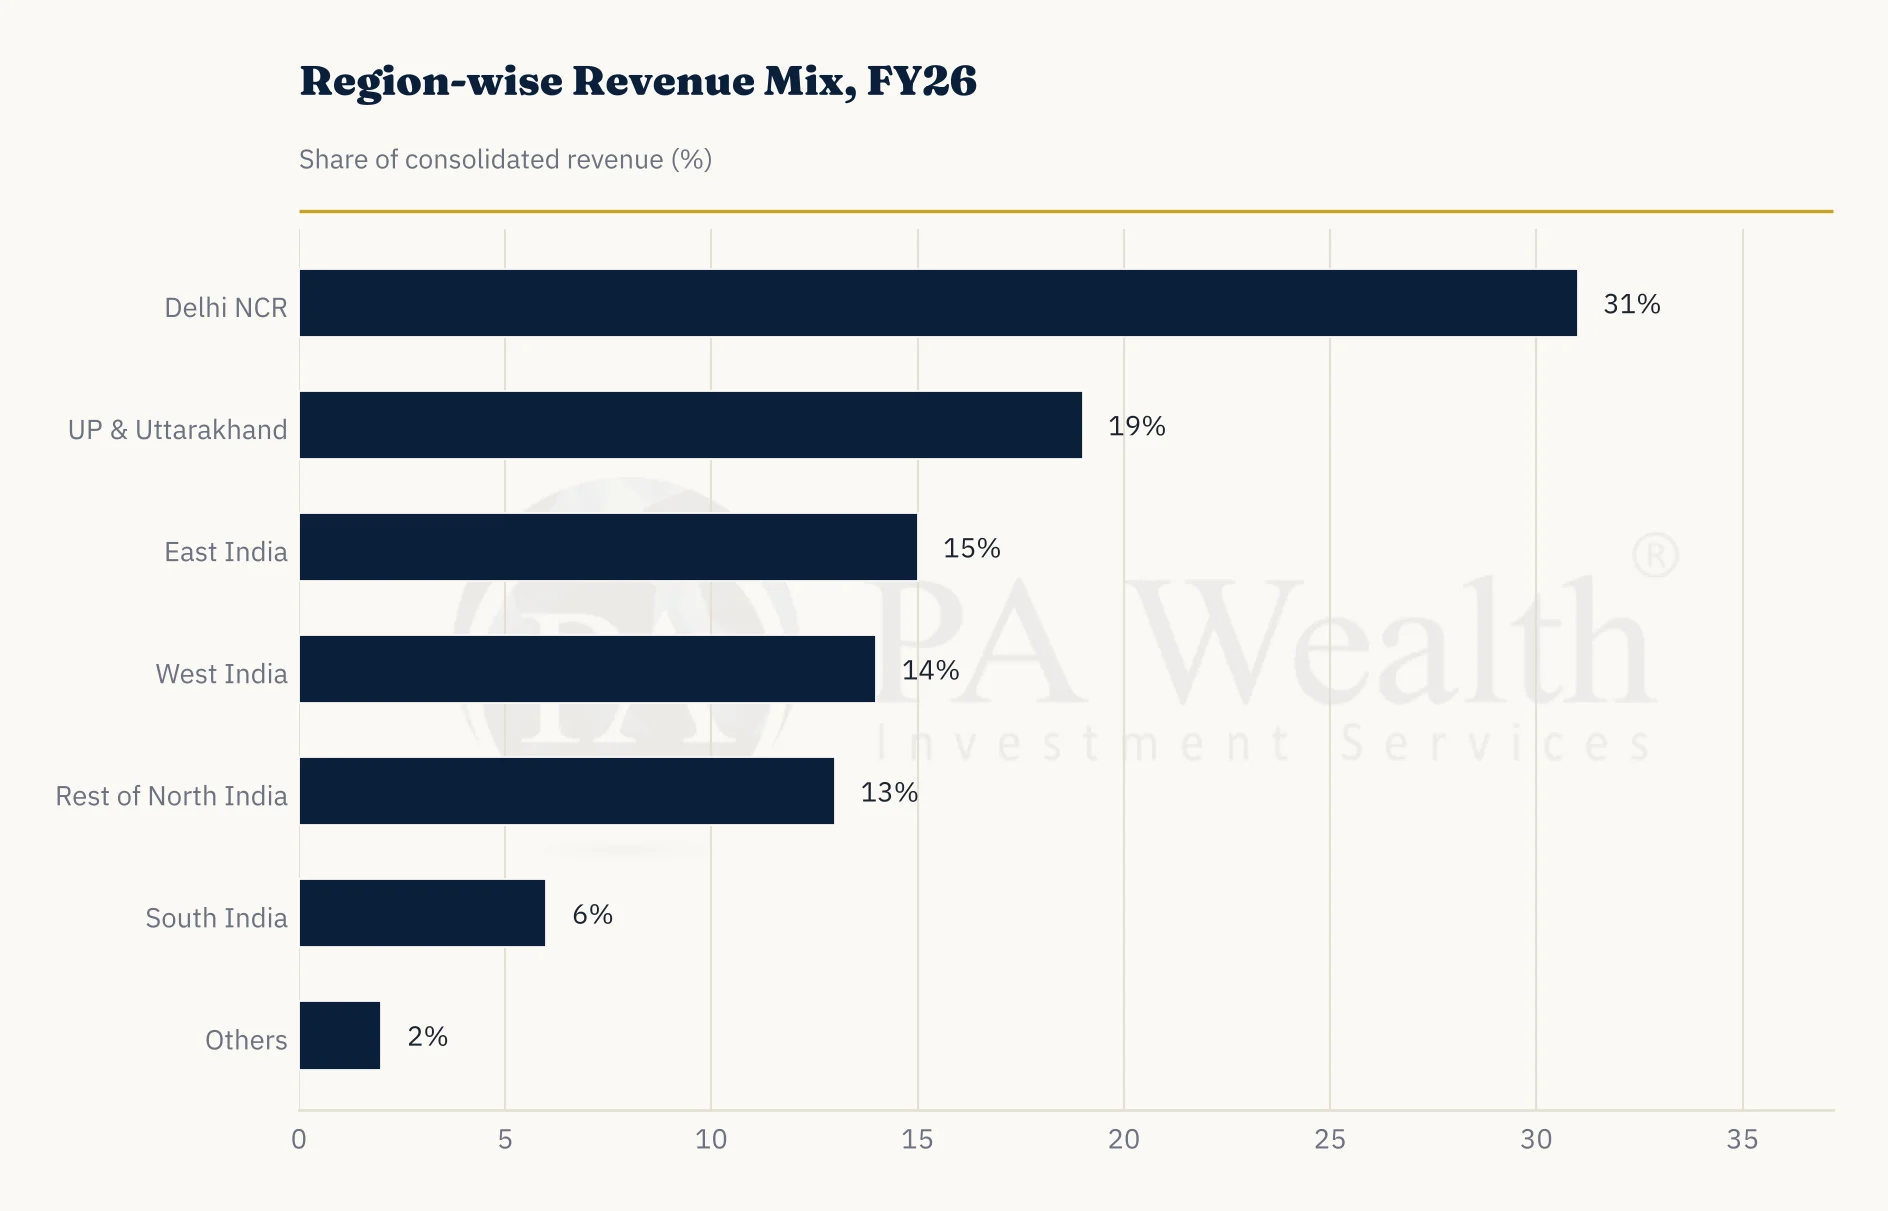
North India is the stronghold: Delhi NCR alone is 31% of revenue and UP and Uttarakhand another 19%, while South India is only 6%. Tier 3 and smaller towns now contribute about 39% of revenue.
(D) Shareholding Pattern
| Category | Jun 2026 (%) | Sep 2026 (%) | QoQ Change |
|---|---|---|---|
| Promoters | 53.19 | 52.93 | -0.26 |
| FIIs | 17.35 | 18.73 | +1.38 |
| DIIs | 21.59 | 21.57 | -0.02 |
| Public | 7.48 | 6.35 | -1.13 |
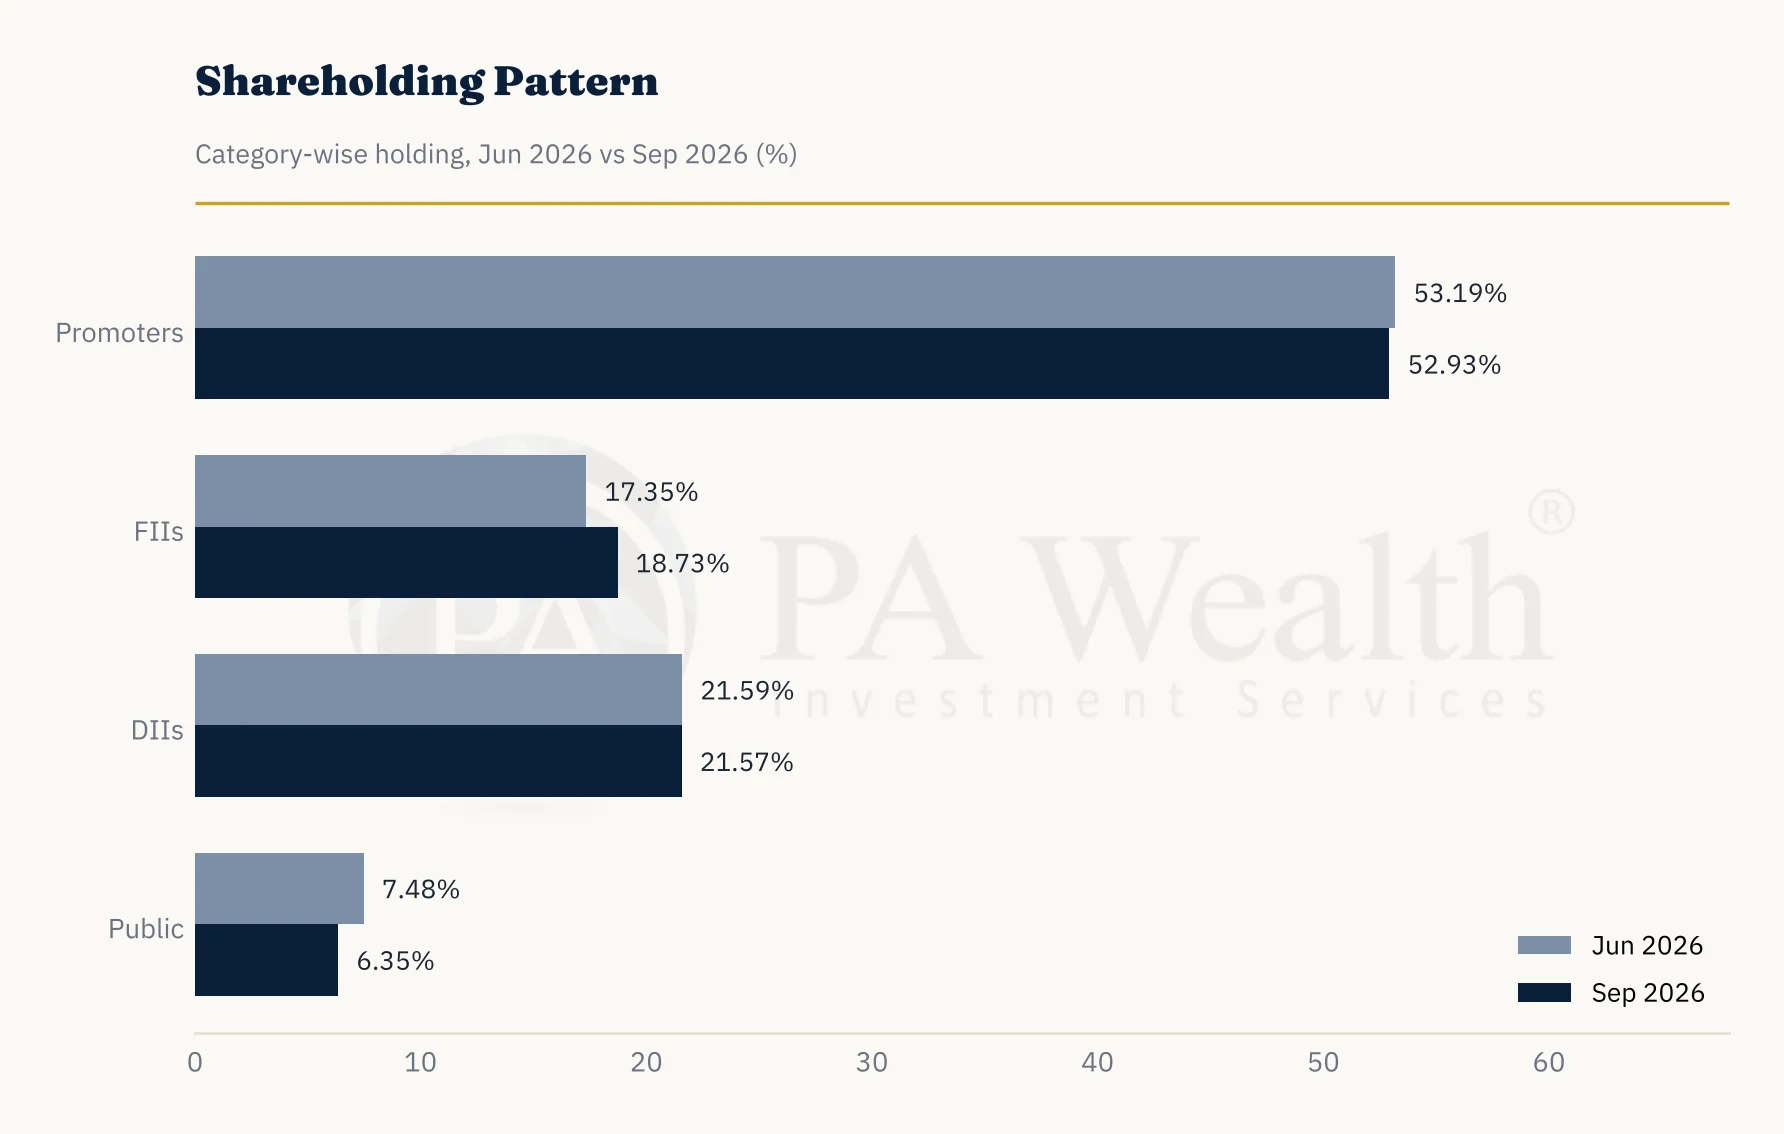
FIIs added 1.38 percentage points in the September quarter, taking institutional ownership above 40%, while retail holding fell.
(E) Financials
Consolidated, Rs crore (EPS in Rs, bonus adjusted).
| Particulars | FY23 | FY24 | FY25 | FY26 | 3-Year CAGR |
|---|---|---|---|---|---|
| Revenue | 2,017 | 2,227 | 2,461 | 2,763 | 11.1% |
| EBITDA | 490 | 609 | 696 | 752 | 15.3% |
| EBITDA Margin (%) | 24.3% | 27.3% | 28.3% | 27.2% | – |
| PAT | 241 | 362 | 492 | 510 | 28.4% |
| EPS (Rs) | 14.4 | 21.5 | 29.2 | 30.2 | 28.0% |
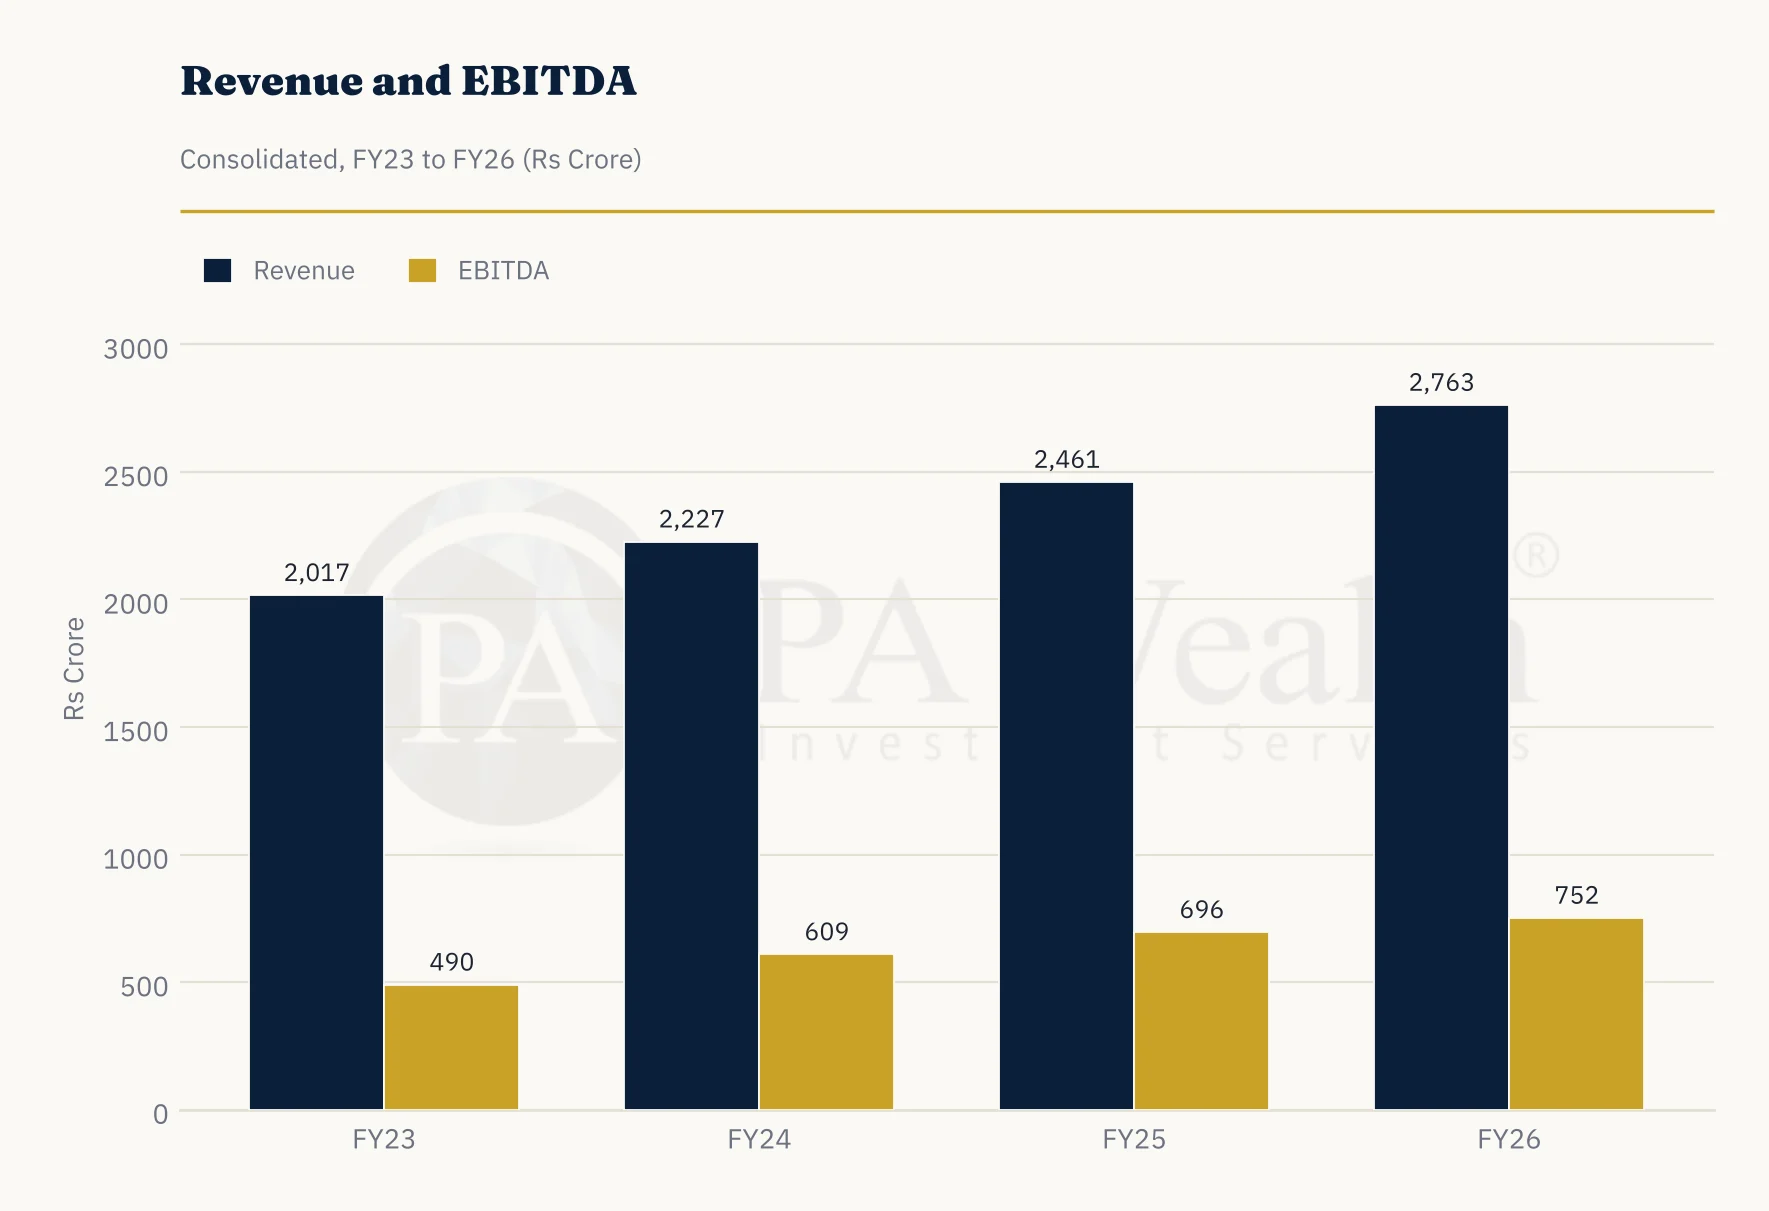
FY23 was a low post-Covid base, which flatters the PAT CAGR. FY26 also carried a one-time Rs 30 crore Labour Code cost, while FY25 had a Rs 41 crore one-time gain. Adjusted for these, FY26 EBITDA grew 12.5% at a 28.3% margin.
The quarterly trend shows the acceleration. After a soft Q3 FY26, revenue rose to Rs 798 crore in Q1 FY27 and Rs 874 crore in Q2 FY27, with PAT at Rs 170 crore and Rs 194 crore.
| Quarter | Revenue | EBITDA | EBITDA Margin | PAT |
|---|---|---|---|---|
| Q1 FY26 | 670 | 192 | 28.7% | 134 |
| Q2 FY26 | 731 | 224 | 30.6% | 152 |
| Q3 FY26 | 660 | 179 | 27.1% | 91 |
| Q4 FY26 | 703 | 187 | 26.6% | 132 |
| Q1 FY27 | 798 | 247 | 31.0% | 170 |
| Q2 FY27 | 874 | About 280* | About 32%* | 194 |
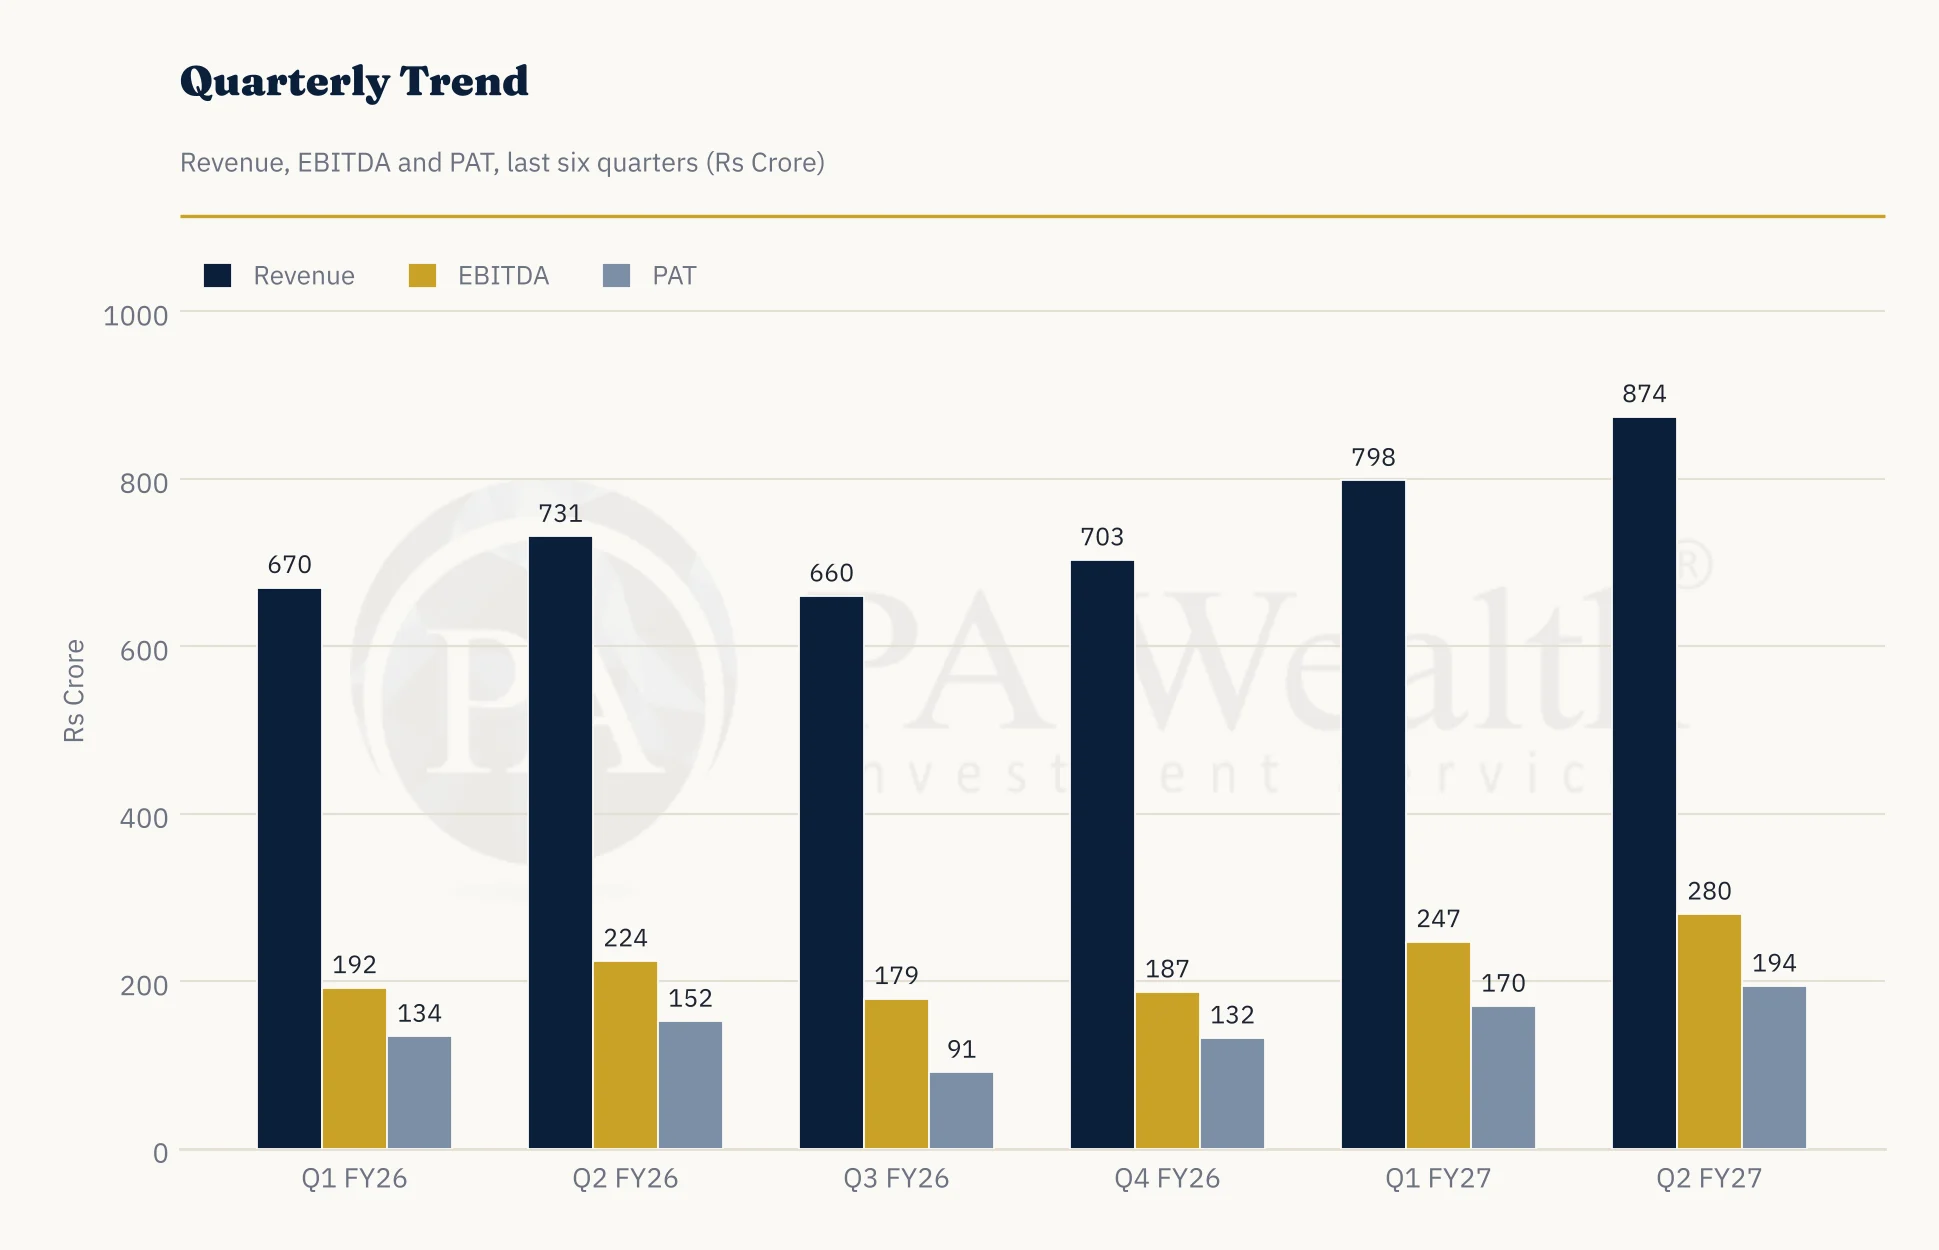
*Our estimate derived from the reported Q2 FY27 results.
(F) Management Discussion and Highlights
- H1 FY27 revenue rose 19.4% to Rs 1,672 crore and PAT rose 27.3% to Rs 364 crore. Q1 FY27 EBITDA margin was 31.0%, up from 28.7% a year ago.
- Growth is broad-based: Q1 FY27 patient volumes rose 8.2%, samples 10.7% (13.6% in Q2), and revenue per patient rose 10% to Rs 968.
- The CGHS and ECHS price revision is adding 2% to 3% to revenue and is expected to last another 2 to 3 quarters.
- Suburban in Mumbai has turned around and is growing close to double digits, and Delhi NCR continues to grow in double digits.
- FY27 guidance is early to mid-teens revenue growth, now likely towards mid-teens, with EBITDA margin of 27% to 28%. Any extra margin will be reinvested in growth.
- 12 to 15 new labs and 3 to 4 radiology centres are planned this year. Capex is guided at about Rs 140 to 150 crore.
- No general price hike in over 3 years. Management sees “significant pricing headroom” and will review pricing after H1 FY27.
- Cash is mainly earmarked for M&A to build scale in West and South India. Recent deals include Shahbazkers (Mumbai), 80% of Sunshine Healthcare (Ghana) and 30% of Neuome Technologies.
- Two interim dividends of Rs 5 each have been declared for FY27 so far.
(G) Strengths and Weaknesses
Strengths
- A 75-year-old trusted brand with clear leadership in North India.
- Asset-light, franchise-led network with 44% ROCE excluding cash.
- About Rs 1,700 crore net cash, giving room for acquisitions.
- Volumes, tests per patient and realisations are all rising together.
- Pricing lever still unused.
Cautions and Key Risks
- Rich valuation at about 58x earnings leaves little room for disappointment.
- Competition from national chains, hospital labs and local labs is likely to stay intense.
- Imported reagents expose costs to currency and supply chain risks.
- International expansion and new formats are early stage.
(H) Outlook
Dr Lal PathLabs looks to be moving from a 10% to 12% grower to a mid-teens grower as its expanded network matures, Suburban recovers and Swasthfit compounds. It still holds two levers: an unused price hike and a large cash pile for acquisitions. The key things to watch are how growth holds once the CGHS benefit fades and how well the cash is deployed. With the stock already priced at a premium, long-term investors should track execution rather than extrapolate two strong quarters.
References: Dr Lal PathLabs Annual Report FY2025-26; Q4 FY26 and Q1 FY27 earnings call transcripts; Q2 FY27 results (4 November 2026).
Disclaimer: This blog is for educational and informational purposes only and should not be considered a recommendation to buy, sell or hold any security. Investments in securities are subject to market risks. Please read all related documents carefully and consult your financial professional before making any investment decision. PA Wealth Ventures Private Limited is a SEBI Registered Research Analyst (Reg. No. INH000020642). Past performance is not indicative of future returns.